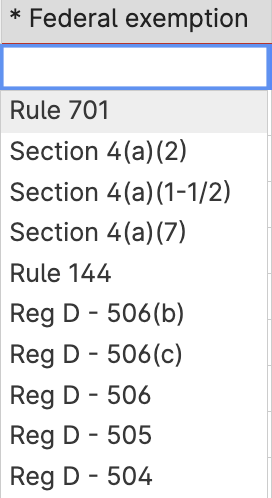
Which federal exemption makes sense when issuing shares to cofounder (Section 4(a)(2) vs. Rule 701)?
Hello Carta Community,
Does anyone know which Federal Exemption applies when issuing stock to a cofounder?
I'm in the process of onboarding my cofounder into my startup and I need to specify a "Federal Exemption" when drafting a stock certificate in Carta. The Carta Support Center offers an overview of the different options and the 2 below seem most appropriate:
Section 4(a)(2)
Rule 701
Carta also lists "Non-US" as an option in the stock issuance form, which also seems applicable because my cofounder is not a US national (nonresident alien). My own digital stock certificate references "Section 4(a)(2)".
Does anyone know which of these 2 make the most sense for issuing cofounder stock? Thank you in advance!